How to Refinance Your Bitcoin-Backed Loan With Arch: A Complete Guide

Head of Marketing, Arch Lending
Already have a Bitcoin-backed loan? You could be paying more interest than necessary. With Arch’s refinancing program, we can beat your existing rate by up to 2%. Refinance an eligible loan by November 30, 2026, and we’ll waive the Arch origination fee.
And you don’t need to sell your Bitcoin or come up with the cash to pay off your existing lender. Arch handles that directly.
A Bitcoin-backed loan gives you access to cash without selling your Bitcoin. But taking out a loan doesn’t mean you’re locked into the same lender, interest rate, or terms forever.
If another lender offers a better deal, refinancing could help you reduce your borrowing costs while maintaining your Bitcoin exposure.
The challenge? Your current lender holds your Bitcoin as collateral. Before you can move it to another lender, the existing loan must be repaid.
That leaves borrowers facing a difficult question: How do you switch lenders without finding the cash to pay off your existing loan first?
That’s where Arch comes in.
For eligible borrowers, Arch pays off the existing lender directly, coordinates the transfer of Bitcoin into qualified custody with Anchorage Digital, and replaces the old loan with a new one.
The result? A potentially lower interest rate, no Arch origination fee, and a simpler way to move your Bitcoin-backed loan without selling your holdings.
This guide covers:
- How Bitcoin-backed loan refinancing works
- How to switch your existing loan to Arch
- What refinancing could save you
- What happens to your Bitcoin during the transfer
- How to compare rates, fees, LTV thresholds, and custody arrangements
- When refinancing makes financial sense
- Frequently asked questions about switching crypto lenders
What Is Bitcoin-Backed Loan Refinancing?
Bitcoin-backed loan refinancing means replacing an existing loan secured by Bitcoin with a new loan, typically from a different lender or under different borrowing terms.
Your Bitcoin remains collateral. The loan agreement changes.
For example, suppose you have a $100,000 Bitcoin-backed loan at a 10% annual interest rate. Another lender offers you a comparable loan at 9%.
Refinancing would allow you to replace the original loan with the new one, potentially reducing your annual interest expense.
On a $100,000 balance, a one-percentage-point reduction represents approximately $1,000 in annual interest savings, assuming the balance stays constant and interest is calculated on a simple annual basis.
The bigger the loan, the more meaningful a rate reduction can become. But refinancing isn’t just about finding the lowest advertised rate. It also gives you an opportunity to reassess where your Bitcoin is held, how your lender manages market volatility, and whether your loan terms still fit your financial goals.
For Bitcoin holders who intend to maintain their position over the long term, those considerations matter.
How Does Refinancing a Bitcoin Loan Work?
Refinancing a Bitcoin-backed loan involves three important transactions:
- Your existing loan is repaid.
- Your Bitcoin collateral is released by the original lender.
- A new loan is established using the transferred Bitcoin as collateral.
The complication is the order in which those transactions happen.
With a traditional secured loan, a refinancing lender may coordinate repayment of the original debt and the transfer of the underlying security. Bitcoin-backed lending presents a similar challenge, but the collateral is a digital asset that may need to move between different custodians or lending platforms.
If you attempt to refinance independently, your current lender may require full repayment before releasing your Bitcoin. That could mean finding $100,000 in temporary liquidity simply to move a $100,000 loan.
Alternatively, you might need to provide additional Bitcoin to the new lender before your existing collateral becomes available. Neither option is particularly attractive if your objective is simply to secure better borrowing terms.
How Arch removes the upfront payoff barrier
Arch coordinates the refinancing process directly. Instead of requiring you to repay your existing loan out of pocket, Arch pays the original lender as part of the approved refinancing transaction.
Once the existing loan is settled, the collateral is released and transferred into Arch’s custody arrangement with Anchorage Digital. Your new loan then replaces the previous borrowing arrangement.
You don’t need to fund the payoff yourself or pledge additional Bitcoin to complete the switch. Eligibility and final loan terms apply.
The result: You can evaluate a better lending arrangement without first having to unwind your entire Bitcoin-backed position.
How to Refinance Your Bitcoin-Backed Loan With Arch: Step by Step
Arch’s refinancing program is designed to make switching lenders straightforward, with support from our team throughout the process.
Here’s what to expect.
Step 1: Review your current Bitcoin loan
Start by gathering the details of your existing loan.
You’ll want to know:
- Your current lender
- Outstanding loan balance
- Interest rate and APR
- Remaining loan term
- Bitcoin collateral amount
- Current loan-to-value (LTV) ratio
- Applicable repayment or exit fees
- Any outstanding accrued interest
These details help establish whether refinancing would improve your position.
For example, a lower interest rate might be attractive, but the full comparison should also account for fees, collateral requirements, and the amount of time you expect to keep the loan.
Step 2: Request your refinancing offer from Arch
Share your existing loan details with the Arch team.
Arch can review your current borrowing arrangement and provide an offer based on your eligibility, loan size, collateral, and applicable lending terms. Our team will show you the rate we can offer, and we’ll waive the Arch origination fee.
The actual offer depends on your loan and eligibility.
Before accepting, review the proposed rate, repayment structure, loan term, LTV thresholds, and any costs associated with the switch.
You should be able to understand not just the advertised rate reduction, but what the new loan will cost over its expected lifetime.
Step 3: Complete verification and accept your new terms
As with other Arch loans, borrowers must meet applicable eligibility and identity-verification requirements.
Once your refinance is approved, review the new loan agreement and confirm that the terms align with your needs.
Pay particular attention to:
- The new principal balance
- The interest rate and APR
- Whether interest is paid periodically or deferred
- Loan maturity and repayment obligations
- Margin-call and liquidation thresholds
- Any applicable fees
The new loan should improve your financial position in a way that makes sense for your circumstances.
Step 4: Arch pays off your existing lender
This is the central benefit of Arch’s refinancing program.
Once the approved refinancing arrangement is ready to proceed, Arch coordinates payment of your outstanding loan to the existing lender.
You don’t need to independently come up with the full payoff amount as part of the standard approved process.
The original lender can then release the Bitcoin securing your previous loan. The exact settlement sequence and timing depend on the original lender’s requirements and the transfer arrangements.
Step 5: Your Bitcoin moves into qualified custody
After the original lender releases your collateral, the Bitcoin is transferred into Arch’s custody arrangement with Anchorage Digital.
Anchorage Digital Bank is a federally chartered digital asset bank regulated by the OCC and a qualified custodian. Eligible collateral is held in segregated custody and is not rehypothecated.
That means Arch does not lend out, trade, or reuse your Bitcoin to generate additional yield. Your Bitcoin continues to secure your borrowing, now under the new loan arrangement.
Step 6: Your new Arch loan goes live
Once the refinance is completed, your new Arch loan replaces your previous loan. You’ll be able to manage your position under the new terms, including monitoring your collateral, outstanding balance, and LTV.
Depending on your loan’s eligibility and structure, Arch also offers features such as early repayment without penalties, loan upsizing, collateral withdrawal, and term extensions.
If your financial needs change later, you can review the options available to you rather than assuming your loan must remain unchanged until maturity.
Ready to see what switching could look like?
Talk to the Arch team about refinancing
How Much Could You Save by Refinancing Your Bitcoin Loan?
Even a relatively small interest rate reduction can produce meaningful savings, especially on larger loan balances.
With Arch’s refinancing program, we can beat your existing rate by up to 2%.
Here’s how a lower rate could translate into interest savings.
Potential annual interest savings
| Outstanding loan | 1 percentage point lower | 2 percentage points lower |
|---|---|---|
| $25,000 | $250 | $500 |
| $50,000 | $500 | $1,000 |
| $100,000 | $1,000 | $2,000 |
| $250,000 | $2,500 | $5,000 |
| $500,000 | $5,000 | $10,000 |
| $1,000,000 | $10,000 | $20,000 |
Illustrative annual interest differences only, assuming a constant principal balance, simple annual interest, and a full 12-month comparison period. Actual savings depend on approved terms, fees, repayment timing, and other costs. The 2-percentage-point column is illustrative, not a guaranteed offer.
For example, refinancing a $250,000 loan from 10% to 9% could reduce annual interest expense by approximately $2,500.
For borrowers managing significant Bitcoin-backed positions, comparing lenders can therefore be a worthwhile exercise.
Don’t compare interest rates alone
The lowest interest rate isn’t always the least expensive loan. When reviewing a refinancing offer, consider the annual percentage rate (APR), which reflects applicable borrowing costs under the relevant calculation methodology.
You should also examine:
Origination fees: Does the new lender charge a fee to establish the loan? Arch is currently waiving its origination fee for refinances.
Exit costs: Does your existing lender charge a prepayment, withdrawal, or settlement fee?
Accrued interest: How much interest is outstanding when the original loan is repaid?
Loan duration: Are you comparing costs over the same period?
Collateral requirements: Will the new lender require more Bitcoin to secure the same loan balance?
Repayment flexibility: Can you repay early, defer interest, or adjust the loan if your needs change?
A useful refinancing comparison should show the total expected cost of keeping your existing loan versus moving to the new lender.
A Real Bitcoin Borrower: How a Michigan Business Owner Lowered His Rate
For some borrowers, refinancing is about more than optimizing a financial product. It’s about making capital more affordable for a real business.
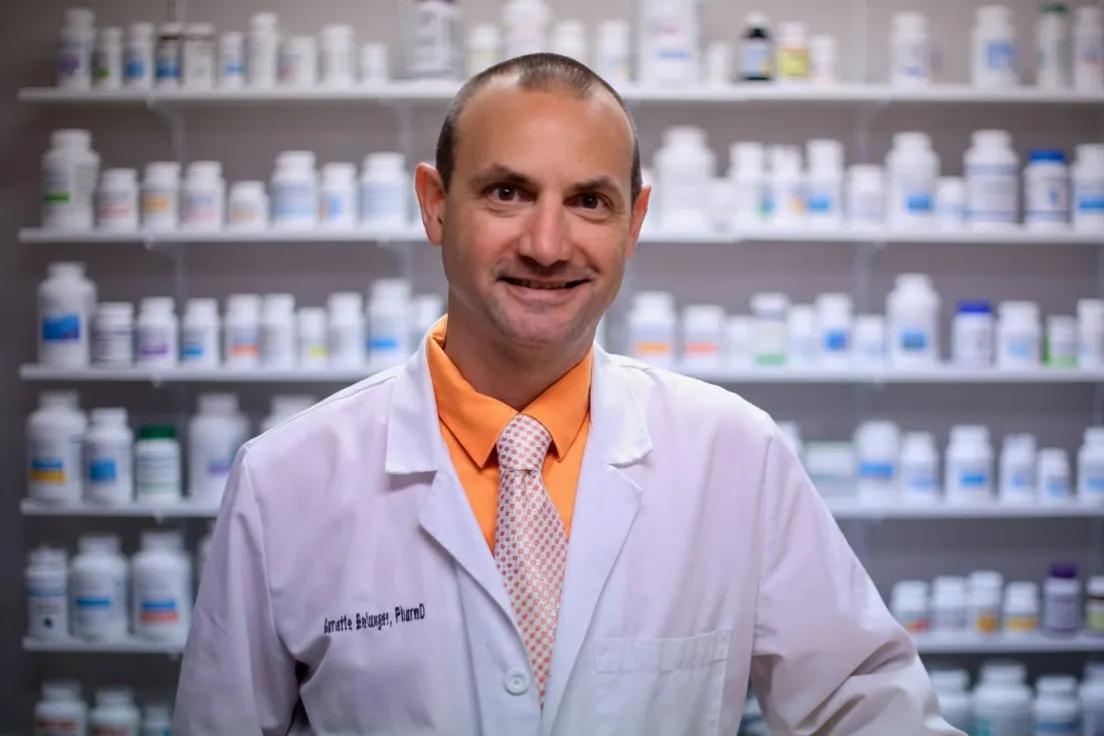
Garrette Belanger, owner of Orange Pill Pharmacy in Michigan, refinanced his Bitcoin-backed loan with Arch and reduced his interest rate by approximately two percentage points.
Belanger is developing a cash-pay pharmacy model intended to make prescriptions available at prices comparable to, or lower than, insurance copays.
Access to capital can help support inventory purchases and business expansion, but he wanted to avoid selling his Bitcoin to fund those needs.
His existing loan presented an obstacle: the original lender was holding his Bitcoin as collateral.
Arch’s ability to repay that lender directly helped make the switch possible.
As Belanger explained, that capability “was a huge deciding factor for me.”
By refinancing, he was able to move his loan to Arch, secure a lower rate, and continue using his Bitcoin as collateral for business financing.
His experience illustrates why refinancing can matter to borrowers who value both their long-term Bitcoin holdings and the cost of accessing liquidity.
Individual borrower results are not guaranteed. Savings and eligibility depend on the loan and approved terms.
What Happens to Your Bitcoin When You Refinance?
When you refinance a Bitcoin-backed loan, the underlying asset doesn’t need to be sold simply because the lender changes. Instead, the collateral is released from the original lending arrangement and moved to secure the replacement loan.
That distinction matters for borrowers who want to maintain exposure to Bitcoin’s potential long-term appreciation. However, transferring collateral between lenders introduces an important consideration: custody. Before switching, understand exactly where your Bitcoin will be held and how it will be managed.
Qualified custody with Anchorage Digital
Arch uses Anchorage Digital Bank, a federally chartered digital asset bank regulated by the OCC and a qualified custodian, to safeguard eligible collateral. Bitcoin securing Arch loans is held in segregated custody rather than being pooled for unrestricted lending or trading activity.
What does no rehypothecation mean?
Rehypothecation occurs when a lender reuses assets pledged by a borrower, potentially to secure other financing or support additional lending activity. That can introduce another layer of counterparty exposure.
Arch does not rehypothecate client collateral. Your Bitcoin is held to secure your loan, rather than being lent onward to generate yield for the platform.
For borrowers evaluating refinancing offers, the custody arrangement deserves as much attention as the headline interest rate.
Understanding Loan-to-Value When Refinancing
Your loan-to-value ratio, or LTV, measures the size of your outstanding loan relative to the market value of your collateral.
The formula is:
LTV = Outstanding loan balance ÷ Current collateral value × 100
For example, if you have a $50,000 loan secured by $100,000 worth of Bitcoin, your LTV is 50%.
If Bitcoin’s price falls and your collateral is worth $80,000, your LTV rises to 62.5%, even though you haven’t borrowed any additional money. This is why LTV matters when comparing refinancing offers.
A lower interest rate may reduce borrowing costs, but the new lender’s margin-call and liquidation thresholds determine how much room your collateral has to absorb market volatility.
What should you compare?
Before refinancing, review three figures:
- Starting LTV: The proportion of your collateral’s value you’re borrowing against when the loan begins.
- Margin-call threshold: The LTV at which you may need to add collateral or repay part of your loan.
- Liquidation threshold: The point at which the lender may sell collateral to reduce its exposure.
Arch offers different LTV structures depending on the asset, loan size, and approved product.
Don’t assume the highest available LTV is automatically the best choice. Borrowing less against the same collateral generally provides a larger buffer against price declines.
Partial liquidation versus full liquidation
If Bitcoin’s price falls significantly, a collateralized loan may become undersecured relative to its agreed terms. Some lending arrangements permit liquidation of an entire collateral position when a threshold is breached.
Arch’s approach is designed around partial liquidation: selling enough collateral to bring the loan back toward its required LTV rather than automatically selling the entire position.
That distinction can matter to borrowers who want to preserve as much of their Bitcoin as possible during volatile markets.
However, partial liquidation still means selling some Bitcoin, potentially incurring fees and tax consequences. Borrowers should review the margin-call and liquidation terms in their loan agreement.
Refinancing does not remove Bitcoin price risk. It gives you an opportunity to choose a loan structure and collateral-management approach that better fit your needs.
Why Refinance With Arch Instead of Staying With Your Current Lender?
A lower rate may be the initial reason to consider switching, but it shouldn’t be the only one.
Arch combines its refinancing program with several features designed for Bitcoin-backed borrowers.
1. Direct payoff of your existing loan
Arch coordinates repayment of the original lender so qualifying borrowers don’t have to independently fund the entire payoff before transferring collateral.
2. Competitive refinancing terms
Arch aims to lower your rate and waives its origination fee.
Your exact terms depend on your loan and eligibility.
3. Segregated custody and no rehypothecation
Eligible collateral is held with Anchorage Digital, and Arch does not reuse your Bitcoin for other lending or trading activities.
4. Partial liquidation framework
If your LTV reaches the liquidation threshold, Arch sells only enough collateral to bring the loan back to a healthy LTV, rather than selling your entire position. Borrowers should review their specific margin-call and liquidation terms before refinancing.
5. Flexible loan management
Eligible borrowers can access features such as:
- Repaying early without a prepayment penalty
- Deferring interest payments until maturity on qualifying products
- Upsizing a loan as collateral value increases, subject to LTV limits
- Withdrawing eligible excess collateral
- Rolling over a loan at maturity, subject to approval and prevailing terms
6. Support from real people
Refinancing an existing loan can involve several moving parts.
Arch provides access to its client services team through live chat and scheduled consultations, so borrowers can discuss their current loan, proposed terms, and transfer process with a specialist.
When Does Refinancing a Bitcoin-Backed Loan Make Sense?
Refinancing may be worth exploring if one or more of the following apply.
You’re paying a higher interest rate than necessary
If your current lender charges more than another lender would for comparable terms, switching could reduce the cost of borrowing.
The potential benefit increases with the size of your loan and the length of time you expect to maintain the balance.
You want a different custody arrangement
If you have concerns about how your current lender holds or uses collateral, refinancing gives you an opportunity to move to a different custody model.
Review the custodian’s regulatory status, segregation arrangements, rehypothecation policy, and relevant legal protections.
You want more flexibility
Your borrowing needs may change over time.
Perhaps you want the option to repay early, adjust your loan amount, or access additional liquidity as your collateral appreciates.
Refinancing can provide an opportunity to choose terms that better accommodate those needs.
You want to reassess your liquidation risk
A lender’s margin-call and liquidation policies can have significant consequences during Bitcoin market downturns.
Switching may give you access to different thresholds or collateral-management procedures, although you should compare the complete risk profile rather than assuming that a higher threshold eliminates risk.
You’re using Bitcoin-backed borrowing to finance a business
For business owners, borrowing costs affect cash flow and the economics of expansion.
Reducing interest expense may free up capital for inventory, operating costs, or growth initiatives without requiring the sale of Bitcoin holdings.
When Might Refinancing Not Be Worth It?
Refinancing isn’t automatically the right decision.
You may be better off keeping your current loan if:
- Your existing rate is already competitive.
- Exit fees or other transaction costs outweigh the expected interest savings.
- You’re planning to repay the loan soon.
- The new LTV or collateral requirements are less suitable for your position.
- Your current lender offers features you would lose by switching.
- The new loan’s repayment schedule or maturity creates additional financial pressure.
For example, saving $500 in annual interest may not justify a switch that introduces $800 in unavoidable costs.
Similarly, a lower interest rate may be less attractive if the replacement loan requires significantly more collateral or changes your risk exposure in a way you’re uncomfortable with.
The goal isn’t simply to switch lenders. It’s to improve the overall economics and structure of your loan.
Bitcoin Loan Refinancing Checklist: What to Review Before You Switch
Before accepting a refinancing offer, work through this checklist.
- Confirm your current outstanding balance and payoff amount.
- Check your existing interest rate and APR.
- Identify any prepayment, withdrawal, or settlement fees.
- Compare the new interest rate and total expected borrowing cost.
- Confirm whether origination fees are waived.
- Review the new loan’s duration and repayment obligations.
- Calculate your starting LTV under the replacement loan.
- Compare margin-call and liquidation thresholds.
- Understand where your Bitcoin will be held.
- Confirm whether the lender rehypothecates collateral.
- Ask how the payoff and collateral transfer will be coordinated.
- Review any potential tax implications with a qualified adviser.
Once you have those answers, you can make a more informed comparison between your current loan and the proposed replacement.
Frequently Asked Questions About Refinancing Bitcoin-Backed Loans
Can I refinance a Bitcoin-backed loan with another lender?
Yes. Subject to eligibility and the terms of your existing loan, you may be able to replace it with a loan from another lender.
Arch offers a refinancing program that coordinates repayment of the original lender and the transfer of eligible collateral.
Do I need to sell my Bitcoin to refinance?
No. An approved Arch refinance is designed to move your collateral from the existing lending arrangement to the new loan without requiring a sale solely to complete the switch.
However, collateral liquidation may still occur under applicable loan terms if LTV thresholds are breached or other contractual conditions arise.
Do I have to pay off my current loan before switching to Arch?
Arch pays the existing lender directly as part of its approved refinancing process.
Qualifying borrowers therefore don’t need to independently fund the entire existing loan payoff.
How much can I save by refinancing?
Savings depend on your current rate, approved replacement rate, loan balance, fees, and remaining borrowing period.
As a simple illustration, reducing the interest rate on a $100,000 loan by one percentage point could save approximately $1,000 over a year if the balance remains unchanged.
Does Arch charge an origination fee for refinancing?
Through November 30, 2026, Arch is waiving its origination fee on eligible new loans used to pay off a qualifying crypto-backed loan from another lender. Promo code SwitchToArch is required.
The offer is subject to eligibility, approval, jurisdiction, final terms, and promotional conditions, and other refinancing costs may apply.
How long does Bitcoin loan refinancing take?
Timing depends on verification, approval, settlement with your existing lender, and the release and transfer of collateral.
Arch coordinates the process, but the exact completion time can vary depending on the original lender and transaction requirements.
Where will my Bitcoin be held after refinancing?
Eligible Bitcoin collateral is held in segregated custody with Anchorage Digital Bank, a federally chartered digital asset bank regulated by the OCC and a qualified custodian.
Arch does not rehypothecate client collateral.
Can I borrow more when I refinance?
Eligible borrowers may be able to increase their loan amount after refinancing, subject to collateral value, applicable LTV limits, and approval.
Can I refinance an Ethereum, Solana, XRP, or tokenized gold-backed loan?
Arch’s refinancing program also covers Ethereum (ETH), Solana (SOL), XRP, Pax Gold (PAXG), and Tether Gold (XAUT) as eligible collateral types, subject to applicable requirements and final loan terms.
Availability and minimum loan sizes vary by asset and jurisdiction.
Does refinancing trigger a taxable event?
Refinancing a loan without selling Bitcoin is not necessarily a taxable disposal, but the tax treatment depends on your circumstances and jurisdiction.
Collateral sales, fees, or other aspects of the transaction may have tax consequences. Consult a qualified tax professional.
Is refinancing the same as rolling over a Bitcoin loan?
No. Refinancing with a new lender generally replaces an existing loan with a new borrowing arrangement. A rollover typically extends an existing loan’s duration, often with the same lender and potentially under updated terms.
Arch offers rollover options for eligible existing borrowers separately from its lender-switching refinancing program.
Ready to Refinance Your Bitcoin Loan? See What Arch Can Offer
See if Arch can lower your Bitcoin loan rate.
Share your existing loan details. We’ll review your terms, show you what refinancing could save, and explain how we handle the switch. Refinance by November 30, 2026, and the Arch origination fee is waived.
Request your refinancing offer from Arch or book a consultation with the Arch team to review your current terms and discuss whether switching makes sense.
Important information: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. All loans and refinancing offers are subject to eligibility, identity verification, jurisdictional availability, collateral requirements, and final loan terms. Interest rates, fees, LTV thresholds, and promotional terms may vary. Digital assets are volatile. Declining collateral values may result in margin calls, required repayments, or partial liquidation under the applicable loan agreement. Review all loan documentation carefully and consult qualified professional advisers where appropriate.